Apple Q3 2026 Earnings: Record Revenue, iPhone Surge, and the Siri AI Bet
Apple (AAPL) reported Q4 FY2026 revenue of $114.5 billion, up 12% year over year and a new September quarter record. Diluted EPS reached $2.10, up 14% from the prior year period. Operating cash flow came in at $28.1 billion, also a record for a September quarter, and gross margin was 47.9%, with tariff benefits contributing approximately 1 percentage point.
The quarter covers the period ending in September 2026, Apple's fiscal fourth quarter and historically its last before the December holiday period. iPhone, Services, and Mac each delivered double-digit year-over-year growth, and Apple's installed base surpassed 2.5 billion active devices for the first time.
Key Numbers
Revenue: $114.5B
EPS: $2.10
Revenue Growth: +12%
iPhone: 17% Growth on a Deep Upgrade Pool
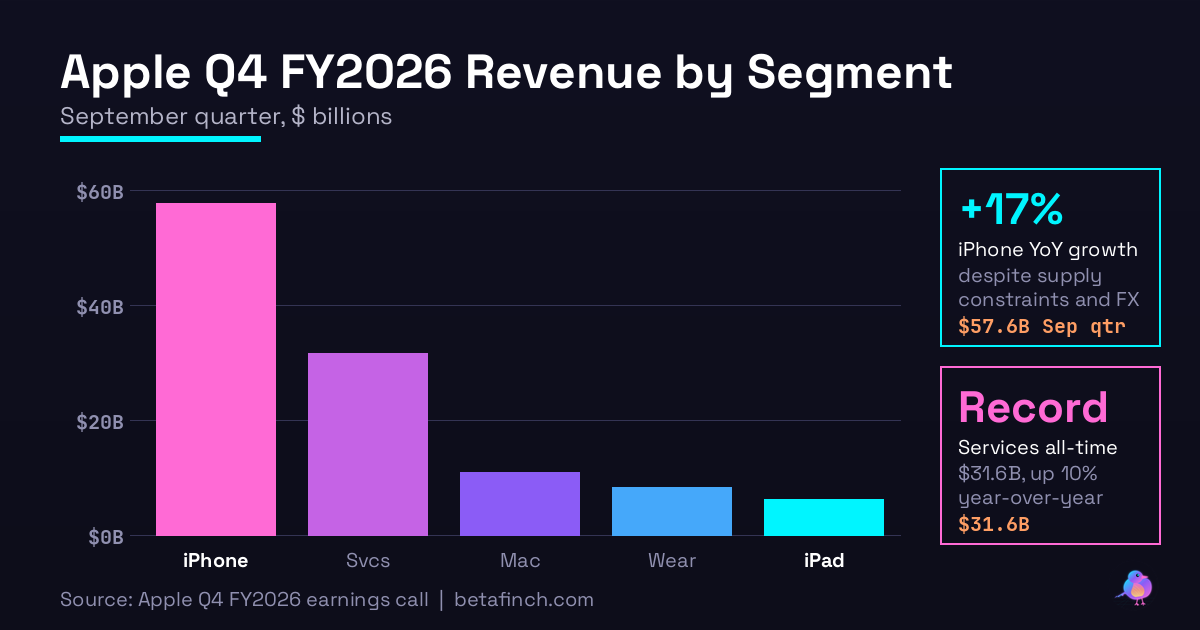
iPhone revenue was $57.6 billion for the September quarter, up 17% year over year despite supply constraints and foreign exchange headwinds. The iPhone Duo launch drove record upgrade volumes in the United States, China, and India simultaneously. Apple management characterized that outcome as a signal that the AI-enabled product refresh resonated across its three largest individual markets.
The 17% growth rate is strong for a mature category in a quarter that typically carries elevated channel inventory as new devices enter the market. Supply constraints, which Apple noted affected availability in some regions, limited the ceiling on the quarter but did not prevent the result from being one of the strongest September iPhone performances on record. Management attributed the result in part to a broadening pool of users on older-generation devices who accelerated their upgrade timelines ahead of the Apple Intelligence feature rollout.
Greater China received specific attention on the call. Revenue in the region grew year over year despite a competitive domestic market, with management citing the installed base as a stabilizing factor and the iPhone Duo as a vehicle for capturing premium-tier trade-ins from older models.
Services: An All-Time Record
Services revenue reached $31.6 billion for the September quarter, up 10% year over year and an all-time record. Apple reported double-digit growth across most geographic markets, a result that reflects both subscriber additions and higher average revenue per user as the subscription bundle deepens.
The Services segment spans the App Store, Apple Music, Apple TV+, iCloud, AppleCare, Apple Pay, and a growing roster of licensed content and financial products. It represented approximately 28% of total company revenue in the September quarter, up from roughly 24% two years ago. Apple noted that paid subscriptions across all services exceeded 1 billion globally, a milestone management has pointed to as validation of the bundle model. Apple TV+ earned additional Emmy wins during the period, reinforcing the content library as a retention driver within the broader bundle. Services gross margin runs considerably higher than hardware gross margin, so the ongoing revenue mix shift toward Services has a compounding effect on the company's overall margin profile.
Mac and iPad: Hardware Breadth
Mac revenue was $10.8 billion, up 24% year over year despite supply constraints. The growth spanned MacBook Air, MacBook Pro, and Mac mini form factors. Apple Silicon continued to extend average selling prices as buyers gravitated toward higher-memory and higher-performance configurations capable of running on-device AI workloads.
iPad revenue was $6.2 billion for the September quarter. The OLED iPad mini attracted attention as the first iPad mini with an OLED display, expanding a form factor that had not seen a panel technology change across several generations. Wearables, Home and Accessories revenue was $8.3 billion. Apple Watch health sensing continued to evolve, with blood glucose monitoring advancing toward broader availability, adding a capability that management has described as a long-term platform differentiator.
Siri AI: The Platform Bet
Apple framed Siri AI and the Apple Intelligence suite as the company's principal platform narrative for the next several years. The architectural approach centers on on-device processing for privacy-sensitive tasks, with a Private Cloud Compute tier for queries that exceed on-device capacity, designed to keep user data out of generalized training pipelines.
The beta rollout progressed through the September quarter, with Apple Intelligence features available on iPhone 16 models, recent iPad hardware, and Macs running Apple Silicon. Management indicated the rollout would expand to additional languages and regions during the December quarter and into 2027. The most-anticipated feature still in beta, Siri's ability to take contextual actions across third-party applications, was cited as a capability that would differentiate the experience from general-purpose AI assistants. Apple executives emphasized the on-device privacy architecture repeatedly during the call as a structural distinction in a market where cloud-based processing has become the prevalent approach.
Installed Base and the December Quarter
Apple's installed base surpassed 2.5 billion active devices, the highest figure the company has reported. The number is relevant to multiple business lines: it sets the ceiling for Services subscriptions, determines the population eligible for Apple Intelligence features, and provides the upgrade demand pool that underpins iPhone revenue in any given quarter.
Management's December quarter commentary pointed to continued iPhone momentum and a broader Apple Intelligence feature set as the primary drivers. Supply chain normalization, following constraints that affected the September quarter, was noted as a variable that could influence hardware availability during the holiday period. Apple did not provide a specific revenue figure for the December quarter, consistent with its recent practice of offering directional framing rather than a numerical guide.
Key Metrics: September Quarter 2026
- Total revenue $114.5B, up 12% year over year, September quarter record
- iPhone revenue $57.6B, up 17% year over year
- Services revenue $31.6B, up 10% year over year, all-time record
- Mac revenue $10.8B, up 24% year over year
- Wearables, Home and Accessories revenue $8.3B
- iPad revenue $6.2B
- Diluted EPS $2.10, up 14% year over year
- Operating cash flow $28.1B, September quarter record
- Gross margin 47.9%
- Active device installed base: over 2.5 billion
For a full breakdown of segment results and management commentary from the earnings call, listen to the <a href="/podcasts/aapl">Beta Finch Apple earnings podcast</a>.