WMT vs TJX Q3 2027 Earnings: Retail Giants Compared
Both Walmart (WMT) and TJX Companies (TJX) reported third-quarter 2027 results that cleared their own guidance bars and prompted upward revisions to full-year outlooks. The overlap ends there. Walmart's quarter was defined by accelerating digital volumes and an expanding store-based fulfillment infrastructure that doubles as a last-mile logistics network; TJX's growth came from breadth, with comparable-store sales increasing across every major division and geography, powered by an off-price sourcing model that gains structural advantage when excess inventory is widely available. The contrast between these two models illustrates how different operational approaches can converge on the same quarterly outcome: results above plan and raised full-year outlooks.
Key Numbers
Revenue Growth: +4.4%
EPS: $2.84-$2.89 (FY guidance)
Ecommerce Growth: +17%
Revenue Growth: +4%
EPS: $1.34
Revenue: $63.8B-$64B (FY guidance)
Walmart: E-Commerce as the Flywheel
Walmart enterprise net sales in constant currency grew 4.4% in Q3, exceeding the top end of guidance of 3%-3.75%. Global e-commerce was the primary driver, rising 17% overall, with the U.S. segment up 23% and Sam's Club up 30%. These numbers reflect volume flowing through a physical store network that acts as a distributed fulfillment system rather than a collection of independent retail locations.
Walmart stores fulfill more than 80% of U.S. e-commerce orders, reaching 96% of U.S. households within three hours and 60% of U.S. households within 30 minutes. Within Q3, store-fulfilled deliveries increased over 40% and expedited deliveries were up more than 50%. The density of that footprint compresses the cost of last-mile delivery in a way that standalone distribution centers cannot replicate, reinforcing the economic case for the omnichannel model at scale.
Membership Mechanics and AI Adoption
Walmart introduced a $120 per year bundled membership combining Walmart+ and Sam's Club Plus, a structure that creates a retention mechanism spanning both retail formats. Membership programs generate recurring revenue that is more predictable than transaction-by-transaction merchandise sales, and they produce behavioral data that informs both the advertising platform and assortment decisions. Higher-margin advertising revenue, which grows with digital traffic, benefits directly from e-commerce volume growth.
AI adoption accelerated materially inside Walmart during Q3. Usage of Sparky, the company's AI assistant, grew 129% year over year, a scale of adoption that points to integration across operational workflows, from search and product discovery to fulfillment routing. Following Q3, Walmart raised full-year sales guidance to 4.9%-5.2%, full-year operating income guidance to 8%-8.6%, and full-year EPS guidance to $2.84-$2.89.
TJX: Broad Comp Growth and International Momentum
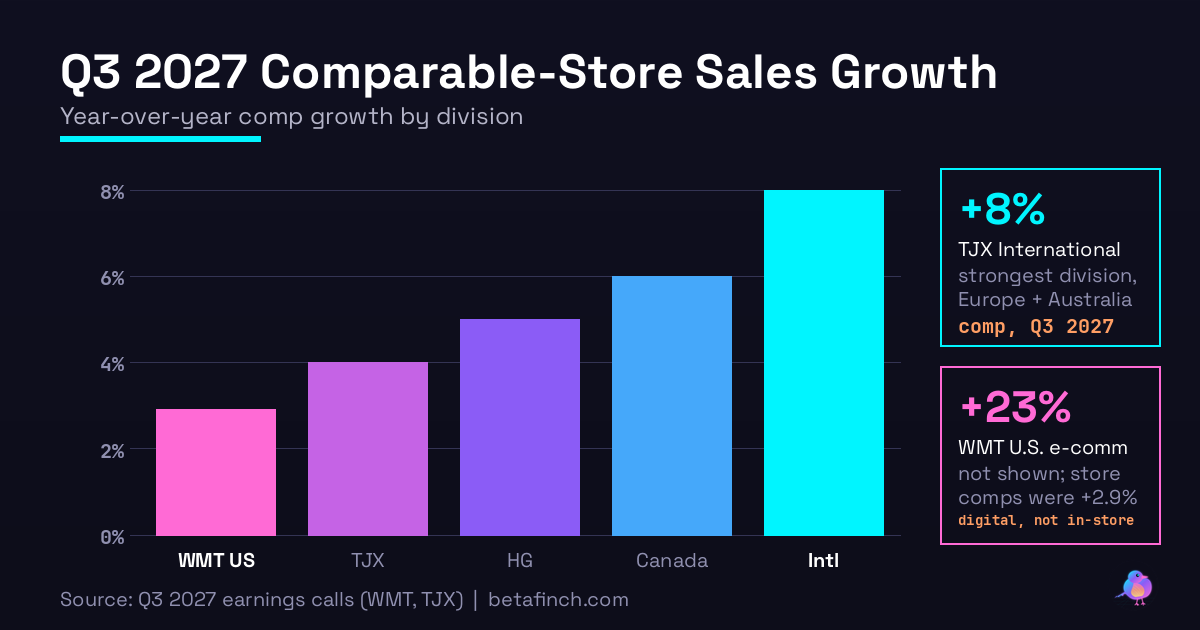
TJX Companies reported Q3 consolidated comparable-store sales growth of 4%, above plan, driven by both customer transactions and a higher average basket. The growth was broad-based across divisions. Marmaxx, the company's largest segment, posted a 2% comparable-store increase. HomeGoods delivered a 5% comp sales increase with segment profit margin of 14.1%, up 60 basis points year over year, a meaningful improvement in a division that experienced freight cost pressure in earlier periods.
The international picture stood out. TJX Canada grew 6% in Q3 and opened its 600th Canadian store during the quarter, a scale milestone for the brand outside the United States. Canada's segment profit margin in constant currency reached 16.1%. TJX International, which includes T.K. Maxx in Europe and HomeSense, grew 8% on a comparable-store basis. That rate of international comp growth outpaced North American segments and suggests the treasure-hunt format is gaining traction in European markets where off-price retail penetration remains lower than in the U.S.
Adjusted diluted EPS for Q3 came in at $1.34, a 5% increase versus the prior year. Adjusted pre-tax profit margin for the quarter was 12.5%. TJX returned $1.5 billion to shareholders in Q3 through dividends and share repurchases.
The Off-Price Structural Advantage
TJX's business model depends on vendor availability, which expands when broader retail inventories are elevated or brands need to manage excess production. That dynamic was favorable in Q3, and management indicated the pipeline of available goods entering Q4 remained plentiful. The treasure-hunt format, in which assortment changes frequently and customers visit more often searching for unexpected finds, creates a traffic pattern that differs from both traditional department stores and subscription-based e-commerce.
Freight costs remain a structural headwind for TJX that Walmart's store-fulfillment model largely bypasses for domestic delivery. TJX ships merchandise from distribution centers to stores, and global freight rates flow directly into cost of goods. The 60-basis-point HomeGoods margin improvement in Q3 signals ongoing recovery from prior freight pressure. TJX raised full-year revenue guidance to $63.8 billion-$64 billion with pre-tax margin guidance of 12%-12.1% and full-year adjusted EPS guidance of $5.17-$5.20.
Holiday Quarter Positioning
Walmart entered Q4 with 7,700 price rollbacks across categories and a delivery infrastructure capable of reaching the majority of U.S. households within hours. The more than 50% expedited delivery growth in Q3 indicates that capacity was expanding alongside demand through the period. For gifting categories and time-sensitive orders, fulfillment speed functions as a competitive variable that is difficult to replicate without Walmart's combination of store density and integrated digital order management.
TJX enters the holiday season with what management described as a strong gifting assortment and the inventory flexibility characteristic of its off-price model. Fresh merchandise flow, a core operating discipline for TJX, sustains visit frequency through the full holiday calendar rather than concentrating traffic around specific promotional events. The 8% International comp in Q3 implies that European TJX formats enter Q4 with momentum, particularly relevant given T.K. Maxx's footprint across the United Kingdom and continental Europe.
What the Results Signal About Retail
Both sets of results point to a consumer environment where transaction volumes are growing but where both price and convenience remain central to purchasing decisions. Walmart's 23% U.S. e-commerce growth, carried by the store-fulfillment model, illustrates that physical retail scale functions as a durable asset in digital commerce rather than a structural liability. The 17% global figure reflects that this dynamic extends across Walmart's international operations as well.
TJX's 4% consolidated comp, broad across segments and geographies, demonstrates that the off-price format maintains relevance across a consumer cycle rather than only during periods of economic stress. TJX Canada's 600th store opening alongside the 8% International comp suggests geographic diversification is contributing to the total comp picture rather than diluting it. For in-depth analysis of both reports, the [Walmart Q3 2027 earnings](/podcasts/wmt) and [TJX Q3 2027 earnings](/podcasts/tjx) podcasts cover each company's quarter in full detail; both also appear in Beta Finch's [retail sector earnings](/groups/retail) coverage.
- Walmart Q3 constant-currency net sales growth: 4.4%, above the 3%-3.75% guidance range
- Global e-commerce: +17% overall; U.S. +23%; Sam's Club +30%
- Store-fulfilled delivery growth exceeded 40%; expedited deliveries up more than 50%
- Walmart full-year EPS guidance raised to $2.84-$2.89
- TJX Q3 consolidated comp: +4%, with HomeGoods at +5% and International at +8%
- TJX Canada opened its 600th store; Q3 adjusted diluted EPS of $1.34, up 5% year over year
- TJX full-year revenue guidance: $63.8B-$64B; adjusted EPS guidance: $5.17-$5.20